Claims guide
Common mistakes to avoid in a hurricane claim
Key takeaways
- Know your policy Read your coverages, exclusions and deductibles before you need them.
- Document early Photos, video and an inventory create a clear record of the damage.
- Report promptly Policies set notice deadlines, so give your insurer written notice without delay.
- Keep everything Save damaged items, receipts and a log of every conversation.
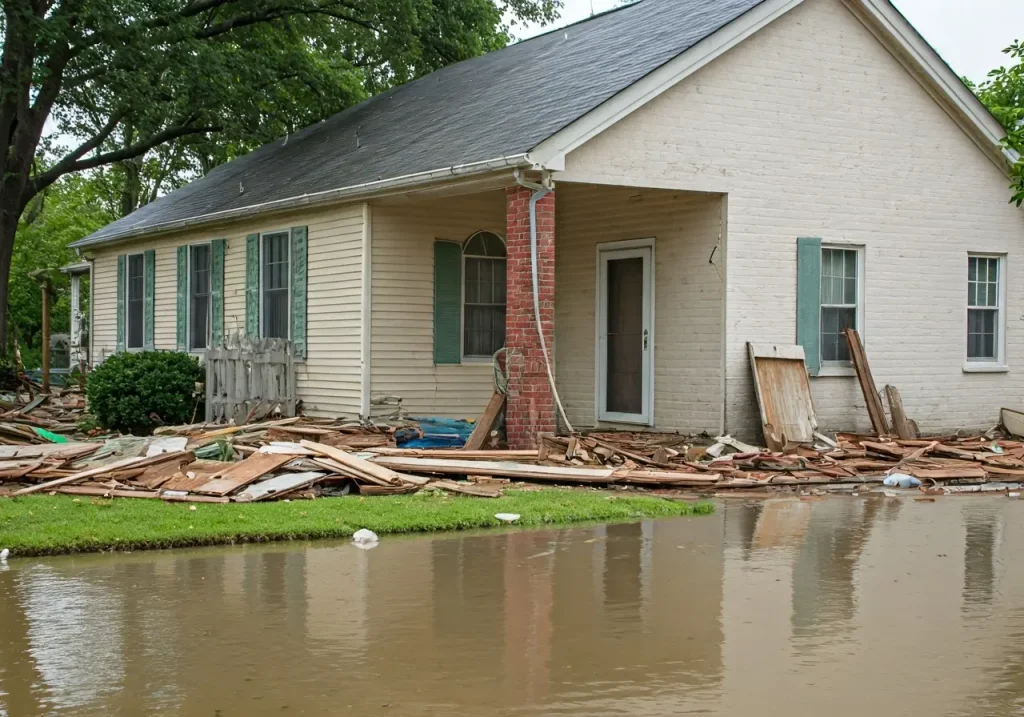
A hurricane can leave a household unsettled for weeks, and the claim that follows often adds to the strain. Many difficulties are not caused by the storm at all, but by small missteps in how the claim is prepared and reported. Understanding them in advance can make a demanding process more orderly.
Not reading the policy
Many homeowners learn what their policy says only after a loss. Coverage limits, deductibles and exclusions all shape how a claim unfolds, and they differ from one policy to the next. Florida policies often carry a separate hurricane deductible, usually expressed as a percentage of the dwelling coverage.
Pay particular attention to exclusions. Standard homeowners policies generally do not cover flood, which is insured separately, so storm surge and rising water are often treated differently from wind damage.
- Coverage limits for the dwelling, other structures and belongings
- The hurricane deductible and when it applies
- Exclusions and any conditions you must meet after a loss
Documenting too little, too late
Once it is safe to do so, photograph and video every area of damage, inside and out. Capture wide shots for context and close-ups for detail. If you have images of the property from before the storm, keep them with your records.
A written inventory of damaged belongings is just as useful. Note what each item is, roughly when it was purchased and where receipts or photos can be found. Label files clearly so they are easy to find later.
Waiting to report the loss
Property policies include notice requirements, and Florida law sets its own time limits for notifying an insurer of a hurricane loss. These rules have changed over the years, so check your policy and current Florida law rather than relying on memory or hearsay.
Giving written notice promptly also creates a clear timeline of events. It does not commit you to anything, and it keeps your options open while you assess the damage.
Discarding or over-repairing too soon
Damaged items are evidence. Keep them, within reason, until the insurer has had a chance to inspect them, or until you have photographed them thoroughly. Throwing things away early can lead to disagreement about what was lost.
Protecting the home from further harm is a different matter. Policies generally expect reasonable temporary measures, such as tarping a roof or removing standing water. Keep receipts for these steps and photograph the conditions beforehand.
Keeping no record of conversations
Claims often involve many calls, emails and visits. Keep a simple log with the date, the name of each person you spoke with and a short summary of what was said. Save all written correspondence, including texts and emails, in one place.
Where possible, follow up a phone call with a brief email confirming what was discussed. A clear paper trail is useful if questions arise later.
Speak with a licensed public adjuster
If you have storm damage in Pasco, Pinellas, Hillsborough or Hernando County and are unsure where to begin, Aviva Insurance Adjusters can explain how the process works. A public adjuster represents the policyholder, not the insurance company. Call 1-877-351-1933 or visit avivapa.com to request a free consultation.
This article is for general educational purposes only and is not legal advice. Every policy and claim is different. Aviva Insurance Adjusters, Corp. is a licensed Florida public adjusting firm (Lic. W869253) and is not affiliated with Aviva plc or any insurance company.